
Alaska’s Mortgage Broker
One application.
We shop wholesale lenders.
Don’t settle for a single bank’s rates. From first-time buyers to seasoned homeowners, we are here to advocate for you from application to closing.
- Low down payment options for qualified buyers
- Low competitive rates and closing costs
- Quick closings when the loan and property allow
Already have a quote? Send it in. We’ll show you how it stacks up.
Locally owned
An Alaska brokerage serving the whole state.
No lender fees*
Wholesale pricing, compared for you.
One credit pull*
Good for 120 days while you shop.
Fully digital*
Apply, upload and sign from anywhere.
*Broker compensation, third-party closing costs, prepaids and escrows still apply; every fee appears on your Loan Estimate. A credit report is generally valid for 120 days, and a lender may run an updated check before closing. Some closings require in-person or notarized signing.
Mortgage help for every stage of owning in Alaska.
Buying your first home in Eagle River or refinancing a cabin on the Kenai — we start from your goals and work back to the right loan.
01
Purchase a home
Loan options, pre-approval letters and fee estimates — plus a second opinion if you're already pre-approved elsewhere.
02
Refinance
Rate-and-term and cash-out refinancing, VA IRRRL, FHA streamline and debt consolidation.
03
Rate comparison
A free side-by-side analysis of what you could save by shopping through a broker.
04
Investor consult
Buy a 2–4 unit property with a low down payment by living in one unit for 12 months.
05
Plan ahead
Not ready yet? We map your path to approval with a soft credit pull — self-employed welcome.
Not sure where you fit? Start with a quick call.
Book a timeUnder the northern lights
Loan programs
for Alaska.
The right loan depends on the home, the place and you. We finance 1–4 unit residential properties.
No HELOCs or commercial loans on 5+ unit buildings. Programs subject to qualification and lender guidelines.
Our Alaska constellation
- Anchorage
- Eagle River
- Chugiak
- Girdwood
- Palmer
- Wasilla
- Kenai
- Homer
- Fairbanks
- Juneau
- Ketchikan
- Sitka
- Kodiak
- Nome
Three steps. One point of contact.
01
Talk it through
A short call about your goals, timeline and budget — by appointment, no obligation.
02
Compare lenders
One credit pull, good for 120 days. We shop wholesale lenders and lay the options side by side.
03
Close with confidence
Upload, sign and track your loan online, with Sveta as your contact start to finish.
A note from Sveta · A broker who works for you, not the bank
Purchasing a home is a big deal. Learn how working with an independent mortgage broker can make one of your most important financial decisions a whole lot easier. Our clients love us for how easy the process is, the speed of the transactions, our expert advice, a touch of humor, and because we actually truly care. ♡
#alaskamortgageteam
Meet the team
Two people, one goal: getting you home. You'll know exactly who to call at every step.
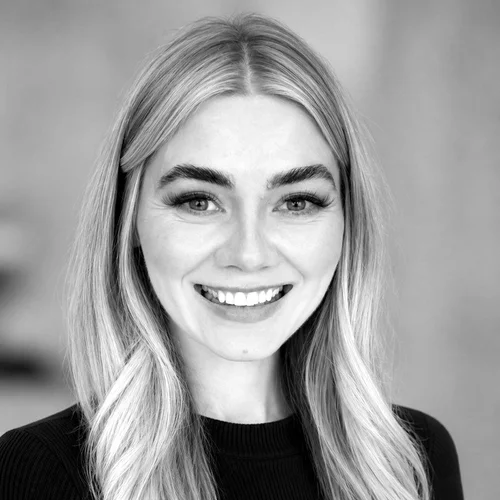
Sveta Cross
Mortgage Loan Originator · Owner · NMLS #1766438
Let’s talk loans…to me, they’re not just numbers on paper, they’re a strategy, a puzzle, and sometimes even a little adventure in finance. I am often told by my borrowers, I don’t just “see” loans like other loan originators. After 15+ years in real estate and lending, I want to know what you want this purchase to make possible, and what you’d hate to give up to make it happen. Whether it’s your first home or a fourplex, I’ll show you where I’d put the cash, where I’d keep it, and what each choice buys you.
How she helps you
Talks through your goals, shops lenders for your loan, and walks you through your options.
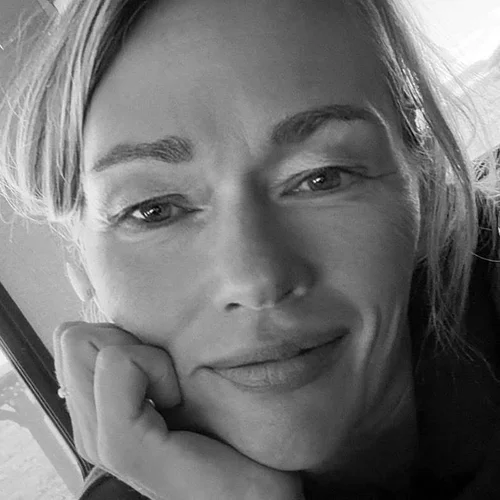
Raegan Rush
Loan Processor
How she helps you
Gathers your documents, keeps your file moving with the lender, and keeps you updated all the way to closing.
Questions I hear from Alaska homebuyers
What if I can't afford 20% down on a house?
You may not need to. Many programs require far less than 20% down: some conventional loans start at 3% for qualified first-time buyers, FHA at 3.5%, and VA and USDA loans can offer 0% down for eligible borrowers and properties.* In Alaska, USDA can be a strong fit in eligible areas like Palmer, Wasilla and the Kenai Peninsula. Call us and we'll find the right program for you.
Do you offer custom loan programs?
Yes. Loan programs change constantly, so we look for the right loan for each client. A bank can only offer its own programs and rates; we work with many wholesale lenders, so we can match you with the lender that best fits your situation. Call us and let us show you what we can do.
Can I use my IRA or 401(k) for a down payment?
Often, yes. Tax rules and penalties for withdrawals and plan loans vary, so talk with your accountant or plan administrator first about the best way to do it. We'll then document the funds for your lender.
What is private mortgage insurance (PMI)?
PMI protects the lender if a borrower defaults. Most conventional loans with less than 20% down require it. Premiums are usually paid monthly, and some lenders offer single-premium or lender-paid options. On a conventional loan you can ask to cancel PMI once your balance reaches 80% of the home's original value, and it ends automatically at 78% if your payments are current. FHA mortgage insurance follows different rules, and your loan servicer has the exact cancellation requirements.
Why use a mortgage broker instead of my bank?
A bank can only offer its own programs and rates. As an independent Alaska broker, we compare many wholesale lenders for your scenario, which can mean a lower rate, lower costs, or approval for a loan your bank doesn't offer.
What credit score do I need to buy a home in Alaska?
Most conventional loans need a 620 score. FHA can go as low as 580 with 3.5% down, and VA minimums are set by each lender.* A higher score usually means a better rate, so it pays to check your options before you start house hunting.
How long does it take to close a mortgage?
Most purchase loans close in about 21 to 30 days from a complete application, and refinances can be faster. Appraisal scheduling can take longer in remote parts of Alaska, so having your income, asset and ID documents ready is the best way to stay on schedule.
What are closing costs, and how much are they in Alaska?
Closing costs include lender and broker fees, title insurance, the appraisal and recording fees, plus prepaid property taxes and homeowners insurance. Alaska has no state real estate transfer tax, which helps. Plan on roughly 2–3% of the purchase price. Every cost appears on your Loan Estimate before you commit.
*For general information only; not an offer to lend or a commitment. Down payment, credit score and eligibility requirements vary by program, lender, property and borrower qualifications. All loans are subject to credit approval.